


Payroll in Malaysia is a monthly filing job, not just paying salaries. If I run payroll, I need to get four things right every month: salary calculations, itemised payslips, statutory deductions, and payment deadlines.
Here’s the short version:
- I calculate gross pay from basic salary, allowances, overtime, bonuses, and leave adjustments.
- I deduct EPF, SOCSO, EIS, and PCB/MTD to get net pay.
- I also pay the employer share for EPF, SOCSO, and EIS.
- I issue payslips on or before payday.
- I submit statutory payments by the due dates:
- EPF and PCB/MTD: by the 15th of the following month
- SOCSO and EIS: by the last day of the following month
- I keep payroll records like payslips, timesheets, bank proof, and submission receipts for 7 years.
A few things can go wrong fast: wrong employee data, poor cut-off dates, bad pay item tagging, or late submissions. For example, a RM3,000.00 employee with 10 hours of normal-day OT and 2 days unpaid leave will not have the same pay as a fixed-salary month. That’s why I need a set payroll calendar, clean employee records, and a final check before release.
At its core, this is what I must manage each month:
- employer registration with LHDN, KWSP, and PERKESO
- employee records, including TIN, EPF number, SOCSO number, and bank details
- pay items and deductions in RM
- monthly remittance dates
- payroll files stored in a clear monthly trail using dd/mm/yyyy
This guide is a plain summary of the parts I need to watch so payroll stays accurate and follows a payroll compliance guide to ensure everything is on time.
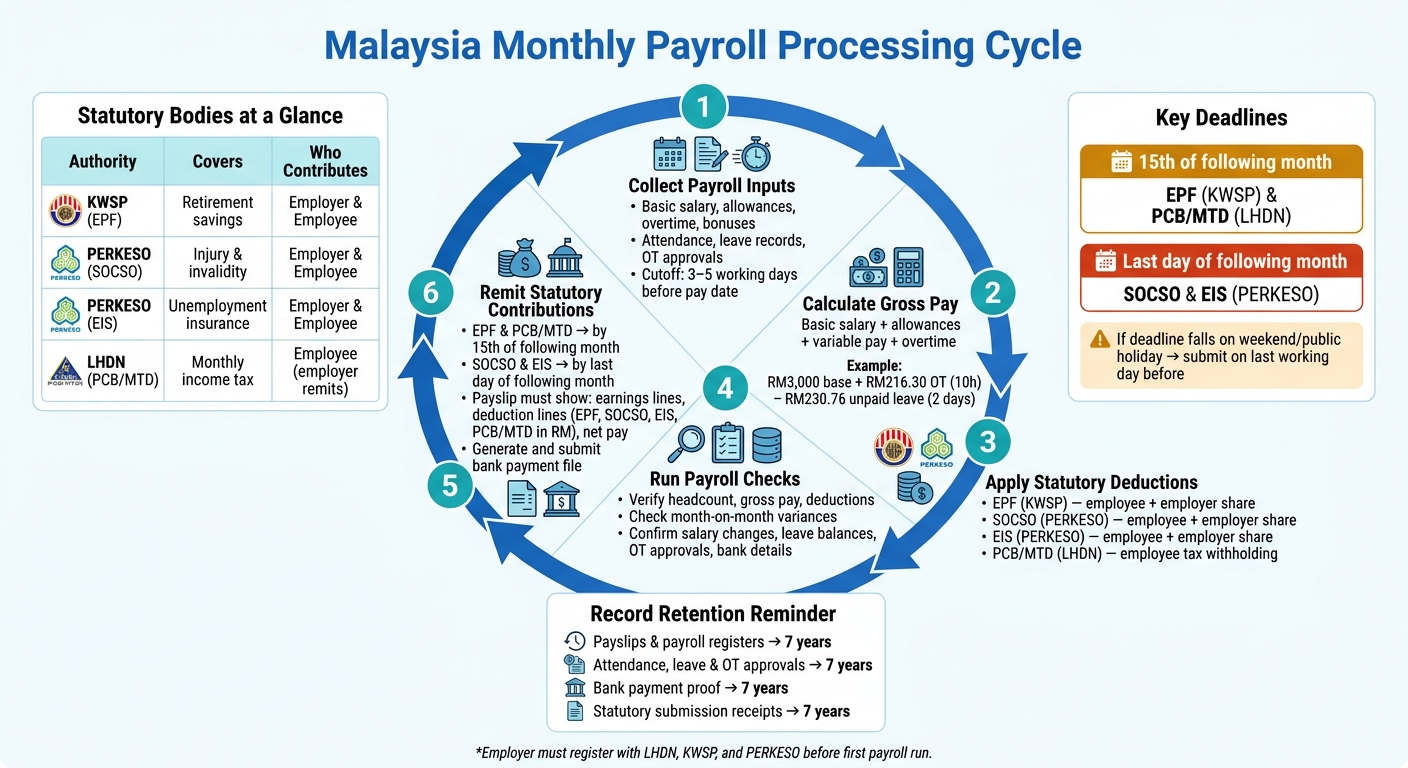
Malaysia Payroll Processing: Monthly Cycle & Statutory Deadlines
Masterclass | The Basics of Payroll in Malaysia
sbb-itb-ba278e7
Malaysia payroll basics
With the monthly cycle in place, the next part is the day-to-day payroll work: the inputs you gather, the calculations you make, and the final output for each pay run.
What employers must handle each month
Each month, employers need to collect the right payroll data before closing payroll. It starts with gross pay, which is made up of basic salary, allowances, overtime, bonuses, and other variable earnings. After that, statutory deductions are applied so you can work out net pay.
Once the figures are checked, employers then:
- generate bank payment files
- issue itemised payslips
- remit contributions to the relevant agencies
Keep rosters, timesheets, payslips, and statutory filing records for at least seven years.
These inputs then feed into the salary calculation step that follows.
Gross pay, deductions, and net pay
Gross pay is the employee’s total earnings before deductions. This includes basic salary, fixed allowances, overtime, bonuses, and taxable benefits where applicable.
Net pay is the amount the employee receives after deductions.
On top of that, employers must also pay their own EPF, SOCSO, and EIS contributions.
Employer registration and payroll setup
Before monthly payroll begins, the employer must be registered and every employee record needs to be set up properly. Once gross pay and deductions are clear, the next step is making sure both employer and employee data are ready for a compliant payroll run.
Before the first payroll is processed, employers need active statutory accounts, complete employee records, and a fixed internal schedule. Miss one of these, and problems can show up fast: backdated contribution payments, missed deadlines, and wrong deductions.
Statutory accounts and employer registrations
There are four statutory bodies every Malaysian employer must register with before the first salary payment is made.
| Authority | Registration Item | Purpose | What to Prepare |
|---|---|---|---|
| LHDN (Inland Revenue) | Employer Number (E) | Monthly Tax Deduction (PCB) and annual returns | SSM registration certificate, company TIN |
| KWSP (EPF) | Employer EPF Account | Mandatory retirement savings contributions | SSM documents, director/owner IC, bank account details |
| PERKESO | SOCSO and EIS employer codes | Employment injury, invalidity, and job-loss cover | SSM documents, director/owner IC |
All these accounts must be active before your first payroll run. If registration is delayed, you may need to make backdated contribution payments. That adds extra admin work nobody wants.
Employee details to collect before payroll starts
For each employee, collect:
- Full name
- IC or passport number
- Address
- EPF number
- SOCSO number
- TIN
- Bank account details
- A signed employment contract showing basic salary, allowances, and start date
For mid-year hires, collect a completed TP3 Form as well. This form records year-to-date income and tax deducted by the previous employer, so PCB can be calculated correctly. Without it, the payroll figure may be off from day one.
Payroll calendar and cutoff dates
Set a fixed payroll calendar early. Use clear internal cutoffs for attendance and leave, usually 3 to 5 working days before pay date, plus deadlines for overtime approval and the final pay date.
It helps to lock these dates in at the start of each year and share them with line managers. Simple? Yes. But it saves a lot of back-and-forth later. These cutoffs feed straight into the monthly salary calculation and payroll approval run.
Salary calculation and monthly payroll run
Once your payroll calendar and employee records are set up, the next step is the actual calculation. A clean payroll run usually follows this flow: earnings, adjustments, deductions, then net pay.
Start with the items that form gross earnings.
Basic salary, allowances, and variable pay
Begin with the basic monthly salary stated in the employment contract. Then add recurring allowances such as transport, meal, mobile phone, and housing, with each one shown as its own line item. After that, include any variable pay earned during the month.
Each item needs to be tagged the right way for EPF, SOCSO, EIS, and PCB/MTD. If those settings are wrong, the statutory figures will be wrong from the very start.
| Category | Examples | Effect on Payroll |
|---|---|---|
| Basic salary | Fixed monthly wage per contract | Starting point for gross pay and statutory calculations |
| Allowances | Transport (RM200), meal, mobile phone, housing | Added to gross pay; tax treatment depends on the item |
| Variable pay / bonus | Sales commission, performance incentive, ad hoc bonus, ex gratia | Added to gross pay for the month paid; check statutory treatment |
| Overtime pay | Normal day OT, rest day OT, public holiday OT | Calculated separately and added to gross earnings |
On the payslip, keep the labels plain and specific. For example: Transport Allowance, OT on Normal Days, or Quarterly Sales Commission.
Overtime, unpaid leave, and bonus calculations
Example: Admin Executive, RM3,000.00 a month, 8 hours a day.
Overtime on a normal working day. Divide the monthly salary by 26 to get the daily ordinary rate of pay (ORP). Then divide that figure by normal daily hours to get the hourly rate. After that, multiply by 1.5 for normal-day overtime.
- Daily ORP: RM3,000 ÷ 26 = RM115.38
- Hourly rate: RM115.38 ÷ 8 = RM14.42
- OT rate (1.5×): RM14.42 × 1.5 = RM21.63
- 10 hours OT in August: RM21.63 × 10 = RM216.30
Payslip line: OT on Normal Days (10h) – RM216.30.
Unpaid leave deduction. If the employee took 2 days of unpaid leave in the same month, the deduction under the 26-day method is RM3,000 ÷ 26 × 2 = RM230.76. This should appear under Deductions as Unpaid Leave (2 days): –RM230.76. If you use this method, put it in your HR policy and apply it the same way every month. That consistency matters.
Bonus. Treat bonuses as variable pay in the month they are paid, and make sure they are flagged correctly before the payroll run starts.
These adjustments need to be right before payroll is released.
Payroll checks before payment
Before payment goes out, review headcount, gross pay, deductions, and month-on-month variances. Then check salary changes, leave balances, OT approvals, and bank details line by line. This may feel a bit tedious, but it is where many payroll errors get caught.
If a figure looks off, pause and review it before releasing payment. A strange variance is usually a sign that something changed, was missed, or was keyed in wrongly.
Use the approved figures for EPF, SOCSO, EIS, and PCB/MTD processing next.
Statutory deductions, contributions, and payroll records
EPF, SOCSO, EIS, and PCB/MTD
After payroll checks are done, move straight to statutory deductions and payroll processing services for remittance.
Once the payroll figures are approved, four statutory items need to be processed before final net pay is released. EPF (KWSP) is a compulsory retirement savings scheme, with monthly contributions from both employer and employee based on wages. SOCSO (PERKESO) covers employment injury and invalidity protection. EIS (SIP), which is also run by PERKESO, provides unemployment insurance. PCB/MTD is the monthly tax deduction sent to LHDN on the employee’s behalf.
Each item has its own rules, so the details matter. Use the current statutory rates and tag each earning item properly so EPF, SOCSO, EIS, and PCB/MTD are calculated on the correct pay base. Overtime, bonuses, and allowances must be tagged the right way too. If not, the deductions can come out wrong. For example, a December bonus increases that month’s EPF and PCB, so statutory deductions should be worked out on total taxable pay, not just basic salary.
| Item | Authority | Purpose | Contributor |
|---|---|---|---|
| EPF | KWSP | Retirement savings | Employer & employee |
| SOCSO | PERKESO | Injury & invalidity protection | Employer & employee |
| EIS | PERKESO | Unemployment insurance | Employer & employee |
| PCB/MTD | LHDN | Monthly income tax withholding | Employee (employer remits) |
Payslips, pay dates, and remittance deadlines
Employers must issue itemised payslips on or before each pay date. A proper payslip should show the employee’s name, ID, and pay period. It should then list each earnings line, such as basic salary, allowances, overtime, and bonuses, followed by separate deduction lines for EPF (employee share), SOCSO, EIS, and PCB/MTD. Each deduction should be labelled clearly in RM.
Net pay should appear at the bottom after all deductions are taken out. It’s also helpful to show the employer’s EPF, SOCSO, and EIS contributions on the payslip, even though those amounts are not deducted from the employee. That gives employees a clearer picture of what is being paid for their benefit. These payslips also make monthly filing and audit checks much easier.
The remittance deadline for all four items is the 15th of the following month. If the 15th falls on a weekend or public holiday, submit on the last working day before it. Miss the deadline, and you may face penalties, interest, and claim issues. These payroll penalties can be substantial for SMEs.
Payroll records and compliance checks
After payment and remittance, file the supporting documents right away. Each payroll month should leave a clean paper trail. The main records to keep are payslips, payroll registers, attendance and leave data, overtime approvals, bank payment proof, and statutory submission receipts from the KWSP, PERKESO, and LHDN portals.
| Record Type | Why Keep It | Retention Period |
|---|---|---|
| Payslips & payroll registers | Employee transparency and dispute support | 7 years |
| Attendance, leave & overtime approvals | Substantiate salary, OT pay, and deductions | 7 years |
| Bank payment proof | Confirm net pay and statutory amounts were paid | 7 years |
| Statutory submission receipts | Evidence of timely EPF, SOCSO, EIS, and PCB remittance | 7 years |
Keep payroll records for 7 years. A simple filing system helps a lot here. Store records by month and by authority so they’re easy to pull out during an audit or when an employee asks about a past payroll entry.
FAQs
What happens if payroll is submitted late?
Late payroll or statutory filings can lead to penalties and extra admin work. Once that happens, you’re not just fixing one mistake. You’re also dealing with follow-up corrections, staff questions, and missed deadlines.
For tax-related filings like Form E and Form EA, there is no grace period.
If Form EA is issued late, employers may face fines of RM200 to RM20,000 and possible imprisonment under the Income Tax Act 1967. On top of that, employees may be blocked from filing their personal income tax returns on time.
Which pay items are taxable or statutory?
In Malaysian payroll, taxable pay items usually include salary, wages, bonuses, allowances, and benefits-in-kind. These make up an employee’s pay and are subject to PCB/MTD.
EPF, SOCSO, and EIS are mandatory statutory contributions. They are not taxable pay items. Employers still need to report salary, statutory deductions, benefits-in-kind, and allowances on Form EA so employees can file their personal income tax accurately.
How should I handle a new hire mid-year?
When you hire a new employee mid-year in Malaysia, add them to payroll straight away and submit Form CP22 to inform the tax authorities.
Starting from their first month of service, register them for EPF, SOCSO, and EIS. You’ll also need to collect their personal details and contract information early, so you can work out their pro-rated salary, statutory deductions, and PCB correctly on the first payslip.