


If I want to open a business bank account in Malaysia, I need three things first: an SSM-registered business, the right documents, and matching details across every form. Most delays happen because one paper is missing, outdated, or inconsistent.
Here’s the short version:
- I can only apply after my business is registered with SSM
- Banks usually accept sole proprietorships, partnerships, and Sdn Bhd
- A sole prop often needs fewer documents than a Sdn Bhd
- For a Sdn Bhd, banks often ask for SSM forms, board resolution, IDs, address proof, and sometimes company stamp and CTC copies
- Banks will check the people who own, control, or can approve the account
- If my business has foreign owners, non-resident directors, or overseas links, checks may take longer
- After approval, I still need to set up online banking, token access, approval flow, and opening deposit
A simple way to think about it:
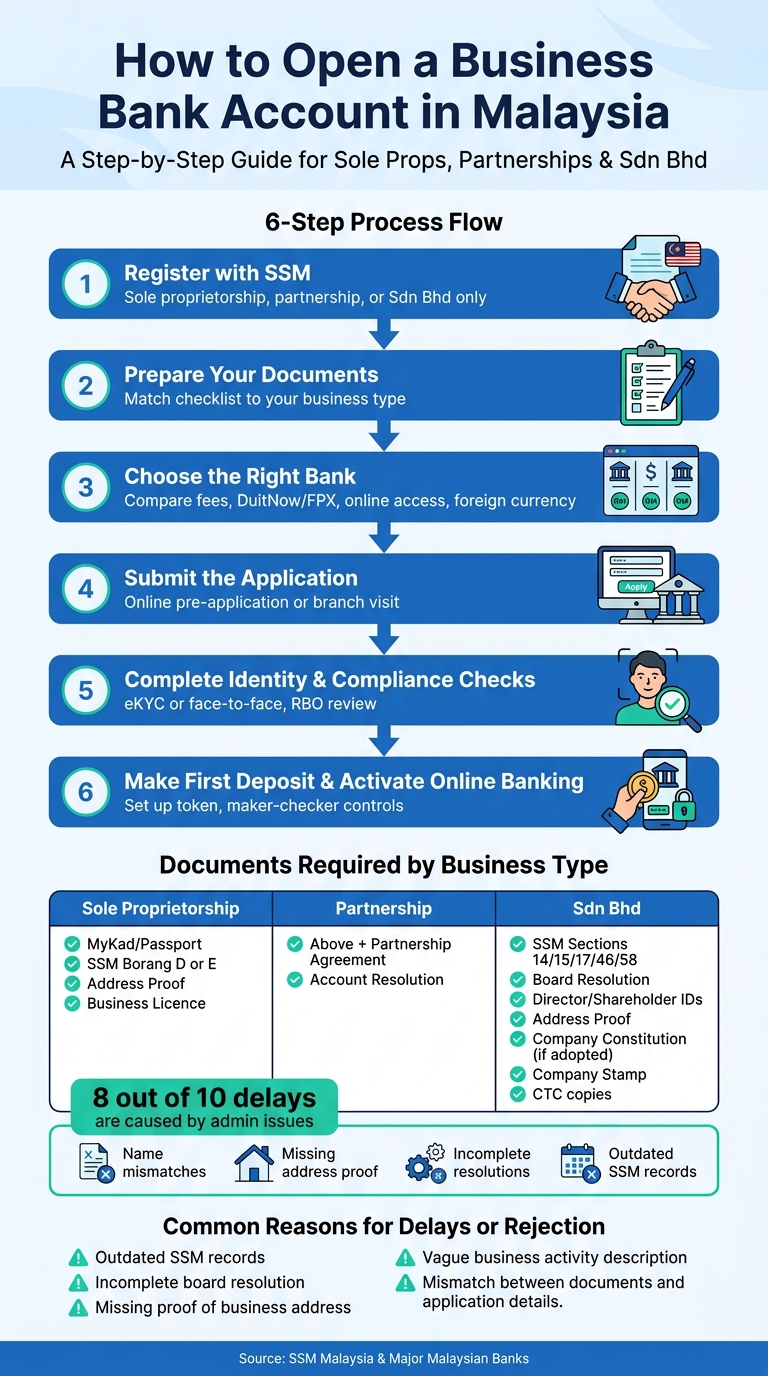
- Register with SSM
- Prepare the right document set
- Choose a bank based on fees, online access, DuitNow/FPX, cash needs, and foreign currency needs
- Submit the application
- Complete identity and compliance checks
- Make the first deposit and activate online banking
About 8 out of 10 account-opening problems come down to admin issues like name mismatches, missing address proof, incomplete resolutions, or old SSM records. So if I want fewer delays, I should check every detail before I submit.
How to Open a Business Bank Account in Malaysia: Step-by-Step Guide
Guide to Corporate Bank Account Opening in Malaysia
sbb-itb-ba278e7
Quick comparison
| Business type | What banks usually ask for | What often slows things down |
|---|---|---|
| Sole proprietorship | MyKad/passport, SSM Borang D or E, address proof, licence | Missing address proof, old SSM renewal |
| Partnership | Same as sole prop, plus partnership agreement and account approval document | Missing partner authorisation, mismatched partner details |
| Sdn Bhd | SSM forms, board resolution, IDs for directors/shareholders, address proof, constitution if adopted | Incomplete resolution, missing stamp, no CTC copies, outdated SSM records |
Bottom line: if I prepare the papers in the bank’s preferred format and make sure all names, addresses, and account approval details match, the process is usually much smoother. The rest is mostly verification and activation.
Check your eligibility before applying
Register your business with the Companies Commission of Malaysia (SSM) before you apply. In Malaysia, banks only open business accounts for SSM-registered sole proprietorships, partnerships, and Sdn Bhd companies.
Once your registration is in place, the next step is simple: match your business structure to the bank’s document checklist. That matters because banks don’t ask every business for the same paperwork.
Business types banks accept
Banks usually accept these business structures:
- Sole proprietorships
- Partnerships
- Sdn Bhd companies
Each structure comes with its own document and signatory rules. A sole proprietorship, for example, is usually more straightforward than a company with multiple directors.
How banks screen directors, owners, and signatories
After checking your business structure, banks move to control and compliance. They screen directors, beneficial owners, partners, and authorised signatories before they approve the account.
Foreign-owned businesses, and those with non-resident directors or signatories, usually face extra compliance checks. That’s one of the main reasons some applications take longer to move through the process.
Documents banks typically require
Once you’ve confirmed your business type and who can sign for the company, get these documents ready first. Try to prepare the full set before you apply. In most cases, delays happen because one or two items are missing. The safest move is simple: match the checklist to your business type, then submit everything together.
Sole proprietorship and partnership document checklist
If you’re a sole proprietor, banks usually ask for your MyKad. If you’re a foreign national, use your passport instead. You’ll also need your SSM Borang D for registration or Borang E for renewal, proof of your business and home address, and any business licence issued by your local council or the relevant sector authority.
For partnerships, the core set stays the same, but banks usually want two more documents: a Partnership Agreement and an account resolution that states who the authorised signatories are.
Sdn Bhd document checklist
For a Sdn Bhd, the document pack is usually larger. Banks often ask for SSM statutory forms such as Section 14, Section 15, Section 17, Section 46, and Section 58. If your company has adopted one, you’ll also need the Company Constitution.
On top of that, prepare a Board Resolution that approves the account opening and names the authorised signatories. Banks also usually request MyKad or passport copies for all directors and major shareholders.
Checklist by entity type:
| Document Category | Sole Proprietorship / Partnership | Sdn Bhd (Private Limited) |
|---|---|---|
| Identity Documents | MyKad or Passport for proprietor / all partners | MyKad or Passport for all directors, signatories, and major shareholders |
| SSM Registration | Borang D (registration) or Borang E (renewal) | Section 14, 15, 17, 46, and 58 |
| Governance | Partnership Agreement (if applicable) | Company Constitution (if adopted) and Board Resolution |
| Authorisation | Account resolution (partnerships) | Board Resolution approving account and signatories |
| Address Proof | Recent utility bill or tenancy agreement | Recent utility bill or tenancy agreement for registered or operating office |
| Operational | Business or sector licence | Sector licences and company stamp |
Use this checklist to prepare your file in the format the bank expects. It sounds basic, but this is where many applications get stuck.
Items that often cause delays when missing
Two items often slow things down: the company stamp and Certified True Copies (CTC) of statutory documents.
Banks may also hold up the application if address proof, IDs, or authorisation documents are incomplete. A missing company stamp can create the same problem. Before you submit, check that these documents are complete and up to date so you can avoid the usual back-and-forth. Once that’s done, you can move on to the application process.
How to open a business bank account, step by step
From SSM registration to choosing a bank account
Start with your SSM registration first, then move on to the bank application.
For a Sdn Bhd, you’ll need to file the Section 14 Superform through the MyCOID portal. This form records your company officers, members, and MSIC activity codes. It sounds routine, but the MSIC part matters more than many founders expect. If the codes don’t match what your business will actually do, the bank may flag it later and your checks can take longer.
Once SSM approves the registration, save and archive your Notice of Registration and Superform extract right away. After that, adopt a board resolution to approve the account opening and name the authorised signatories.
Before you submit anything to the bank, shortlist the account that fits how your business will run. Focus on things like:
- expected transaction volume
- signatory setup
- online payment needs
Application, verification, approval, and first deposit
After Sdn Bhd incorporation and the board resolution, submit the application. Some banks let you start with an online pre-application and may also support remote onboarding, which can save time.
At the verification stage, the bank will usually carry out either a face-to-face meeting or an eKYC identity check. This is where small mismatches can become a headache. Make sure the names and signatory details match across your MyKad or passport, SSM records, and the board resolution.
The bank’s compliance team may also review your Register of Beneficial Owners (RBO) as part of its compliance checks.
Once the application is approved, activate online banking straight away. Then fund the account with the required opening deposit. The amount depends on the bank and the product you chose. After the deposit clears, the account becomes active.
Activate online banking and payment controls
As soon as the account goes live, set up online banking and register your security token, whether that’s a hardware token or a mobile-based one.
If more than one person needs to approve payments, set up a maker-checker or dual-control approval flow from the start. This gives you tighter control over outgoing funds and helps avoid messy approval habits later.
Once those controls are in place, the account is ready for payroll, supplier payments, and day-to-day record-keeping. It also helps to link your accounting system early. If you wait too long, you may end up spending extra time and money backfilling old transactions.
Compare Malaysian banks and avoid common delays
Account features that matter for SMEs
Compare each bank based on how your business runs from day to day.
That sounds simple, but it saves a lot of hassle. A company that collects cash every evening won’t need the same setup as a B2B firm that mainly sends invoices and gets paid by bank transfer. So before you submit any application, trim your bank shortlist using the account features that affect your daily work.
| Feature | Why It Matters for SMEs |
|---|---|
| Minimum initial deposit | Affects how much cash you need to set aside when opening the account |
| Monthly account fees | Affects your monthly running costs |
| Online application availability | Helps if you want a faster process and fewer branch visits |
| DuitNow and FPX support | Helps with collections, supplier payments, and customer transfers |
| Multi-user approval controls | Useful if you need maker-checker approval for outgoing payments |
| Payroll integration | Helps speed up salary runs and statutory submissions |
| Cash deposit machine access | Matters for cash-heavy businesses |
| Foreign currency support | Useful for overseas payments and receipts |
Match these features against your expected transaction volume, number of signatories, and whether you need foreign currency handling. If your team has more than one approver, for example, multi-user controls can save a lot of back-and-forth later on.
Common reasons applications are delayed or rejected
Once you’ve shortlisted a bank, check the common rejection points before applying.
Most delays happen because documents are missing, out of date, or don’t match each other. It’s rarely one big issue. More often, it’s a small mismatch that slows everything down.
| Reason for Delay or Rejection | Preventive Action |
|---|---|
| Outdated SSM records | Update your SSM particulars before applying |
| Incomplete board resolution | Prepare the required board resolution in advance |
| Missing proof of business address | Keep recent proof of business address ready |
| Vague business activity description | Make sure your business activity is clearly described in the application |
| Mismatch between documents and application details | Cross-check names, company particulars, and signatories before submission |
A quick cross-check before submission can make a big difference. Pay close attention to company names, registration details, business address, and signatories so the forms and supporting papers line up cleanly.
How LBCO can support the process
If your documents aren’t ready yet, sort them out before you apply. LBCO can prepare your incorporation papers, resolutions, and statutory records before bank submission. LBCO also supports branchless account opening through partner banks, which can cut down on branch visits.
Conclusion: Getting your business account ready faster
After you’ve compared banks and got your documents in order, the last part is simple: submit everything cleanly and follow up fast. Once the paperwork is set, the process is usually pretty straightforward.
Pick the bank that matches your transaction volume, approval flow, and payment needs.
If the bank asks for extra checks or verification, reply as soon as you can. Keep your SSM particulars and LHDN tax number (TIN) up to date too, since banks may ask for them during compliance checks. If paperwork is slowing things down, LBCO can help get the documents ready before you apply.
LBCO can prepare your Sdn Bhd incorporation checklist and support the bank account opening process.
At the end of the day, faster approval usually comes down to three things: good preparation, complete documents, and prompt replies to the bank’s checks.
FAQs
How long does approval usually take?
Approval time for a business bank account in Malaysia isn’t fixed. It can vary a lot depending on the bank and your company profile.
Your company incorporation might be done in as little as 3 days, but that doesn’t mean the bank account will be approved right away. After registration, the bank will still run its own compliance and verification checks.
To help avoid delays, get your paperwork ready early. That includes documents like board resolutions and director details. Just as important, make sure everything is consistent across the documents. Small mismatches can slow things down.
Can I open the account fully online?
Yes, it may be possible to open a business bank account in Malaysia fully online, without going to a bank branch.
Some banks now offer a simpler remote process, so you can set up your business banking without an in-person appointment.
Do all directors need to be present?
It depends on the bank’s rules. Some banks want all directors to be there in person for ID checks and account signing. Others may let you complete the process without going to a branch.
Before you apply, check the bank’s policy on director attendance. That can save you time and help you avoid a last-minute trip.