


If I start a Malaysian SME, I can’t stop at incorporation. I still need to track SSM filings, company secretary deadlines, licences, bank setup, bookkeeping, EPF, SOCSO, EIS, PCB, corporate tax, and e-Invoicing rules – and some of these start within 7 days, 30 days, or by the 15th of the next month.
Here’s the short version of what matters most:
- Before incorporation: I need to choose the right structure, prepare director/shareholder details, set paid-up capital, pick business activities, and confirm the registered office.
- Right after incorporation: I should appoint a company secretary for a Sdn Bhd, open a bank account, keep statutory and accounting records, and check licences before I trade.
- When I hire staff: I need to register for EPF, SOCSO, EIS, and get my LHDN employer number for PCB.
- For company tax: I need a corporate tax file, track my financial year end, submit CP204, and file Form C on time.
- For monthly and yearly deadlines: I need one calendar for payroll deductions, annual return, financial statements, employer forms, and register updates.
- For e-Invoicing: I should check my turnover band and confirm the latest LHDN rollout date, because the rules have changed in phases.
A few dates stand out straight away:
- EPF registration: within 7 days of hiring my first employee
- SOCSO registration: within 30 days
- EPF / SOCSO / EIS / PCB payments: generally by the 15th of the following month
- Form E: by 31 March
- Form C: 7 months after financial year end
- Annual Return: within 30 days of the incorporation anniversary
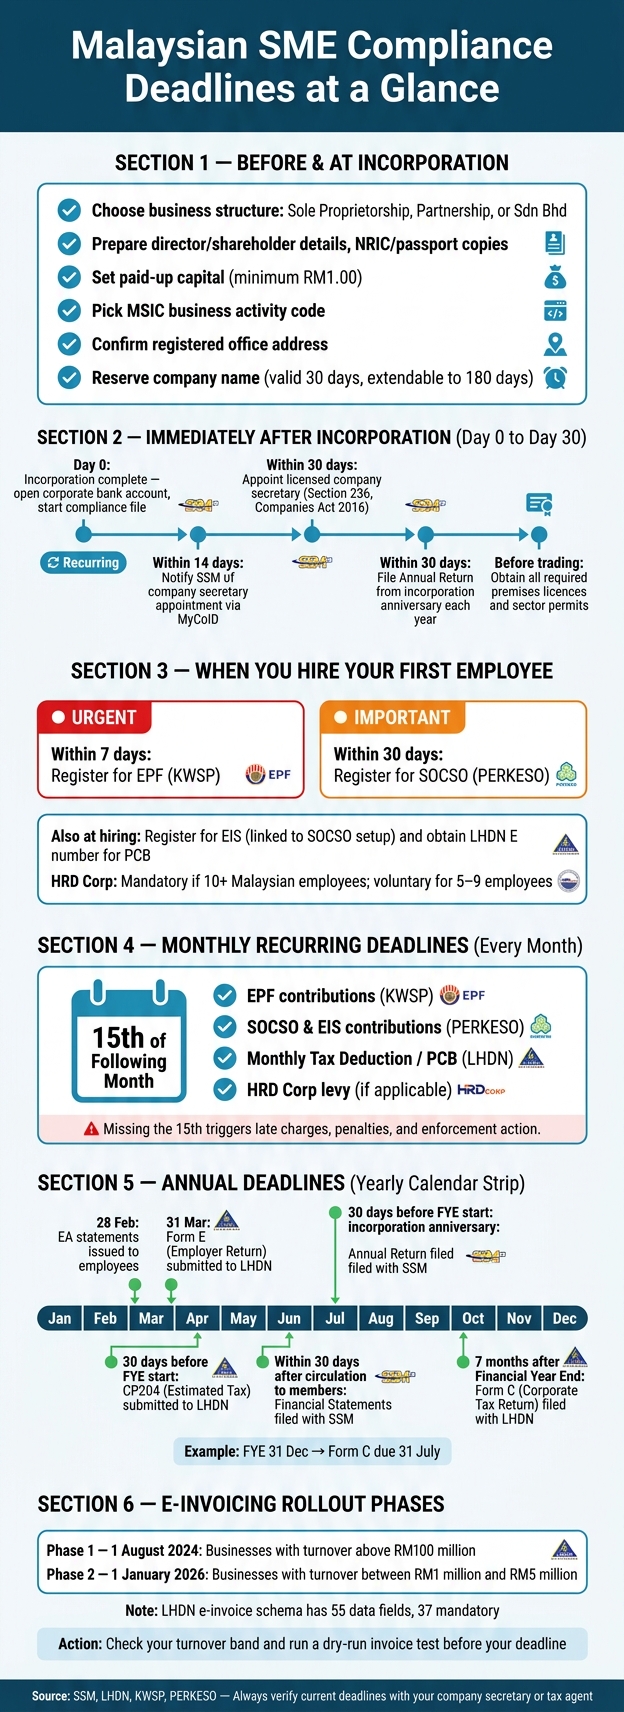
Malaysian SME Compliance Deadlines: Key Dates at a Glance
Quick Comparison
| Area | What I need to do | Main deadline |
|---|---|---|
| Incorporation | Choose structure, prepare SSM details | Before filing |
| Company secretary | Appoint for Sdn Bhd and notify SSM | Within 30 days, then filing after appointment |
| Bank and records | Open account, keep company documents and accounts | Soon after incorporation |
| Licences | Check council and sector permits | Before trading |
| Employer setup | Register EPF, SOCSO, EIS, PCB | 7 to 30 days after first hire |
| Monthly payroll filings | Pay EPF, SOCSO, EIS, PCB | 15th of following month |
| Corporate tax | CP204 and Form C | Based on financial year |
| Annual company filings | Annual Return, financial statements, Form E, EA | Yearly fixed dates / anniversary dates |
| e-Invoicing | Check turnover threshold and LHDN phase | Based on rollout band |
Bottom line: if I give each deadline one owner, keep one document file, and review the calendar every quarter, I cut the risk of fines, late charges, and filing trouble.
sbb-itb-ba278e7
1. Before and during incorporation: choose your structure and understand the filing burden
Choose the right business structure and understand the filing burden
Your first compliance call is incorporating your business and choosing the right structure. That choice shapes your liability, tax position, and how much admin work you’ll carry from day one.
| Sole Proprietorship | Partnership | Sdn Bhd | |
|---|---|---|---|
| Legal status | Not a separate legal entity | Not a separate legal entity | Separate legal entity under the Companies Act 2016 |
| Who registers with SSM | Individual owner via ezBiz | Partners via ezBiz | Usually filed through MyCoID by a company secretary |
| Liability | Unlimited personal liability | Unlimited personal liability, joint and several | Limited to unpaid share capital |
| Tax treatment | Personal income tax | Profits are allocated to partners and taxed personally | Corporate tax; qualifying SMEs may enjoy a lower rate on the first RM150,000 of chargeable income |
| Recurring compliance | Annual renewal with SSM and simple record-keeping | Annual renewal with SSM and simple record-keeping | Annual return, financial statements, statutory registers, company secretary, SSM filings |
| Setup cost | From RM30–RM60 | From RM30–RM60 | Higher upfront and ongoing compliance cost |
Use this table as a quick reality check before you register. If you’re a micro-trader or freelancer, a sole proprietorship or partnership may be enough. If you need limited liability, bank financing, or stronger standing with investors and counterparties, a Sdn Bhd usually makes more sense.
Prepare the details and documents SSM will require for incorporation
Before incorporation, lock in these details:
- Proposed company name – Pick a name that is not already taken and that follows SSM naming rules. If you want to use a coined or non-standard word, SSM may ask for a reason. Reserved names stay valid for 30 days and can be extended up to 180 days.
- Business activities and MSIC code – State your main and secondary activities clearly and choose the right MSIC code. For example, 62010 for computer programming or 56101 for restaurant operation. This can affect licensing and tax incentives.
- Registered office address – You must have a Malaysian address. Many founders use their company secretary’s office address at the start.
- Directors’ details – You need at least one natural person director who is aged 18 or above and ordinarily resides in Malaysia. Prepare the full name exactly as per NRIC or passport, identification number, residential address, and contact details.
- Shareholders and shareholding split – You need at least one shareholder. Decide the number of shares, any share classes, and the ownership split. For instance, 100,000 ordinary shares at RM1.00 each, with one founder holding 70,000 and another holding 30,000.
- Paid-up capital – The legal minimum is RM1.00. That said, some banks and certain licences may expect a higher amount.
- Company constitution – This is optional under the Companies Act 2016. If you do not adopt one, the default rules in the Act apply.
- Supporting documents – Get the basic documents ready: scanned NRIC for Malaysian directors and shareholders, passport for foreigners, and proof of residential address such as a utility bill or tenancy agreement.
This part is a bit like packing before a flight. If one item is missing, the whole trip slows down.
Appoint a company secretary and set key dates from day one
Under Section 236 of the Companies Act 2016, every Sdn Bhd must appoint a licensed company secretary within 30 days of incorporation. The appointment must then be notified to SSM through MyCoID within a further 14 days. This is your first repeating compliance duty as a new Sdn Bhd.
A company secretary handles the statutory side of the business. That includes keeping statutory registers, preparing board and shareholder resolutions, and filing required documents with SSM, such as the annual return. For example, they can prepare the board resolution needed to open a corporate bank account and record any changes in directors, shareholders, or share capital.
The practical move is simple: appoint the company secretary during incorporation, not after. It saves time and helps you avoid missing the 30-day deadline.
After incorporation, the next items on the list are your bank account, licences, records, and bookkeeping.
2. Post-incorporation setup: bank account, licences, records, and accounting
Open a corporate bank account and organise core company records
With incorporation done, move straight to banking, licences, and record-keeping.
Once your Sdn Bhd is incorporated, opening a corporate bank account should be one of the first things on your list. Banks usually ask for your SSM Notice of Registration, the Superform, a board resolution that approves the account opening and names the authorised signatories, plus NRIC or passport copies for all directors and signatories. Some banks may also ask for proof of business address or a copy of your company constitution, if you adopted one.
One small detail can slow everything down: make sure the board resolution matches the bank’s mandate wording. If the wording doesn’t line up, the bank may put the application on hold.
At the same time, set up a compliance file and keep it tidy from day one. Include your SSM incorporation documents, board resolutions, the Register of Members, the Register of Beneficial Owners (RBO), and your minute book. Banks and auditors may ask for these records. You should also keep accounting records, receipts, invoices, and other supporting documents for at least 7 years.
Check business premises and sector licences before you start trading
Before you start trading, check whether your business needs premises licences, sector permits, or both. This part often gets missed, especially by first-time founders who assume incorporation alone is enough. It isn’t.
Here are some common examples:
| Business Activity | Usual Authority | Common Licence or Permit |
|---|---|---|
| General Office / Retail | Local Council (e.g. DBKL, MBPJ) | Business Premises & Signboard Licence |
| Food & Beverage (F&B) | Local Council / Ministry of Health | Premise Licence, Food Handler Permit, Halal Certification (if applicable) |
| Education / Tuition Centre | Ministry of Education (MOE) | Educational Institution Permit |
| Logistics / Transport | APAD / Ministry of Transport | Carrier Licence |
| Import & Export | Royal Malaysian Customs Department | Customs registration via Dagang Net |
| Regulated Professional Services | Relevant Professional Body (e.g. MIA, Bar Council) | Practice Certificate / Firm Licence |
If you’re not sure what applies to your business, check with the relevant local authority directly.
Set up bookkeeping from month one to avoid tax and filing problems later
Once your records are in place, start bookkeeping right away.
Set up your books from month one so you don’t have to backfill transactions later. It sounds boring, but it saves a lot of trouble. Put simple SOPs in place early for invoice approvals, expense rules, and document retention. At minimum, keep invoices, receipts, bank statements, vouchers, payroll records, and fixed asset registers in one filing system.
You should also record the commencement of business date in a board resolution. That date starts the three-month countdown for submitting your CP204 tax estimate to LHDN.
Keeping your books up to date also makes monthly reconciliation for EPF, SOCSO, EIS, and PCB much easier. If your monthly records don’t match year-end forms like EA, CP8D, and Form E, that mismatch can trigger LHDN audits.
3. Employer and tax registrations: EPF, SOCSO, EIS, LHDN, PCB, and e-invoicing
Once payroll starts, record-keeping shifts from one-off setup work to monthly statutory filings.
Register as an employer and set up monthly payroll compliance
At this point, the company is no longer just a newly incorporated entity. It is now operating as an employer.
When you hire your first employee, register for EPF within 7 days, SOCSO within 30 days, and EIS through the same employer setup. You should also register with LHDN to get your E number for PCB and annual employer reporting.
For some sectors, HRD Corp also comes into play. Employers with 10 or more Malaysian employees must register, while those with 5 to 9 can do so on a voluntary basis. If your business meets the HRD Corp threshold, add it to the same compliance calendar so nothing slips through.
EPF, SOCSO, EIS, PCB/MTD, and HRD Corp payments are generally due by the 15th of the following month. That shared date helps, but each item is still its own filing.
The table below sums up the key points for each scheme:
| Scheme | Registration Trigger | Monthly Due Date | Late Payment Risk |
|---|---|---|---|
| EPF | Within 7 days of hiring first employee | 15th of the following month | Late charges and enforcement action |
| SOCSO | Within 30 days of hiring first employee | 15th of the following month | Penalties and compliance issues |
| EIS | Linked to SOCSO employer setup | 15th of the following month | Late payment and non-compliance risk |
| PCB/MTD | When paying taxable employee remuneration | 15th of the following month | Penalties on underpayment or late remittance |
| HRD Corp | 10 or more Malaysian employees must register; 5 to 9 may register voluntarily | 15th of the following month | Levy arrears and enforcement |
Treat these as separate obligations, even if they land on the same payroll cycle.
Complete LHDN tax registration and understand your recurring tax duties
Apart from employer registration, your company also needs its own corporate income tax file with LHDN. This is separate from the employer E number. Corporate tax is based on company profits, while PCB is deducted from employee salaries.
One early choice can shape your filing calendar for years: your financial year end (FYE). Pick it with care, because your Form C deadline falls 7 months after your FYE. For example, if a startup chooses 31 December as its FYE, its Form C will be due on 31 July the next year. That is simple to track. If your business earns more in certain parts of the year, a different FYE may fit your operations better.
On a monthly basis, keep payroll records, invoices, contracts, bank statements, and tax working papers sorted by month and by type – payroll, tax, sales, purchases, and statutory notices. That makes it much easier to respond if LHDN asks for documents or starts a review.
Get ready for Malaysia e-invoicing before your deadline arrives
Malaysia’s e-invoicing rollout is happening in phases based on annual turnover. The first phase started on 1 August 2024 for businesses with turnover above RM100 million. Businesses with turnover between RM1 million and RM5 million came under scope from 1 January 2026. If your SME is near or within these bands, this is not something to park for later.
LHDN’s current e-invoice schema has 55 data fields, and 37 are mandatory. That is why it helps to test one full invoice flow from start to finish: customer data, approval, submission, and retrieval. A dry run often shows where the messy bits are.
Once these registrations are live, the next task is keeping every filing on its recurring deadline.
4. Monthly and annual compliance calendar for Malaysian SMEs
Monthly checklist: payroll, tax deductions, bookkeeping, and licence expiry checks
Once payroll and tax registrations are active, these tasks come back every month.
Each month, you need to file payroll deductions, update your books, and review licence and permit expiry dates. EPF, SOCSO, EIS, and PCB contributions are all due by the 15th of the following month. Miss that date, and you could face late charges and penalties. Many businesses consider payroll outsourcing in Malaysia to automate these submissions and avoid such risks.
Annual checklist: SSM annual return, financial statements, tax filing, and statutory register updates
Once the monthly routine is under control, the next layer is your annual filings. These sit across different agencies, and following an SSM compliance checklist ensures each one is handled by the right person by the due date.
| Authority | Filing / Obligation | Frequency | Typical Deadline | Owner | Risk |
|---|---|---|---|---|---|
| SSM | Annual Return (AR) | Annual | Within 30 days of incorporation anniversary | Company Secretary | High – compounding fees and prosecution |
| SSM | Financial Statements (FS) | Annual | Within 30 days after circulation to members | Directors / CoSec | High – compounding fees |
| LHDN | Corporate Tax (Form C) | Annual | 7 months after Financial Year End | Tax Agent / Directors | Very High – 15%–45% fine |
| LHDN | Estimated Tax (CP204) | Annual | 30 days before start of financial year | Tax Agent / Directors | High – tax increases |
| LHDN | Employer Return (Form E) | Annual | 31 March | Employer / Payroll | Medium – fines and audit risk |
| LHDN | Employee Statement (EA) | Annual | 28 February (to employees) | Employer / HR | Medium – fines |
| KWSP | EPF Contributions | Monthly | 15th of the following month | Employer / Payroll | High – interest and fines |
| PERKESO | SOCSO & EIS | Monthly | 15th of the following month | Employer / Payroll | High – interest and fines |
| LHDN | Monthly Tax Deduction (PCB) | Monthly | 15th of the following month | Employer / Payroll | High – fines |
One item founders often miss is the Register of Beneficial Owners (RBO). Keep the directors’, shareholders’, and beneficial owners’ registers up to date, and lodge any beneficial ownership changes in SSM’s e-BOS without delay.
You should also review audit exemption status every year under SSM Practice Directive 10/2024. Don’t assume an exemption from last year still applies this year.
Conclusion: one checklist, one document file, and one owner for each deadline
Use one calendar, one document file, and one owner list so every due date stays in plain sight. Put one owner in charge of each recurring deadline, keep one document folder for each compliance category, and review the full calendar at the start of every quarter. That simple setup helps cut missed filings and lowers penalty risk.
FAQs
Do I need a company secretary for every business type?
No. In Malaysia, only companies such as a Sdn Bhd must appoint a qualified company secretary registered with SSM, as required under the Companies Act 2016.
Sole proprietorships and partnerships do not have this specific requirement because they are not incorporated as companies under the Act.
What happens if I miss a compliance deadline?
Missing a compliance deadline in Malaysia can lead to financial penalties and legal consequences.
For tax filings, LHDN may impose penalties under Section 112(3) of the Income Tax Act 1967. The penalty is typically 15% for delays of up to 12 months, 30% for delays from 12 to 24 months, and 45% for delays beyond 24 months.
For SSM filings, such as Annual Returns and financial statements, late submission may trigger enforcement action or compound fines.
How do I know if e-Invoicing applies to my SME?
Whether e-Invoicing applies to your business comes down to your current business size and LHDN’s rollout phases.
If you run an SME, it’s smart to get ready early. Make sure your bookkeeping and payroll systems can handle e-Invoicing without a hitch. Timelines and rules may shift, so check LHDN’s latest announcements and confirm your business entity’s status and rollout timing with your accounting service provider.